
Person Name Member name
23423423
fasdf
Makes $23/year
Premium$45
Financial Help-$66
Monthly payment$77
This is to test the Banner Cyclone namessss
Subheader Optional supporting description below the headline.
Help On Demand is for new enrollment only. If you already have a Covered California case, please contact your certified enroller if you have one, or call our service center at (800) 300-1506 for assistance.
Please fill in your contact information below.
Required fields are marked with an asterisk (*).
Here’s the fine print: A response time of 15 minutes or less is expected during normal business hours (9 a.m. to 5 p.m.). After those hours, and on weekends and holidays, callbacks are based on certified enroller availability, and may occur the next business day.
A Certified Enroller is an expert advisor who is a Covered California Certified Insurance Agent, Certified Application Counselor or a Certified Enrollment Counselor that provides enrollment assistance to consumers.
By sending us your contact information, you understand that it will be transmitted to a certified enroller who will contact you to provide enrollment assistance. When you submit this form, you agree to receive phone calls, texts or emails regarding health insurance from the certified enroller who receives your contact information. You may receive such calls or texts even if you are on the National Do Not Call Registry. Such calls or texts may use an automated telephone dialing system, but you will speak to a live certified enroller if you opt to receive a phone call through Help On Demand. Your phone carrier's normal rates for receiving calls or texts apply.
This is not a condition of obtaining health insurance. Do not continue with this form if you do not agree to these conditions.
This tool is for people who have been offered a Health Reimbursement Arrangement (HRA) by an employer to help pay for health insurance. If you are offered certain types of HRAs, you may not qualify for a tax credit to help purchase a Covered California plan. This tool will help you determine how the HRA you're offered affects your eligibility for a tax credit and what to do next.
There are several types of HRAs, and only some of them require you to use this tool. If your HRA requires use of this tool, you should have received a clear written notice from your employer explaining the terms of the HRA. You will need that notice, along with information to help estimate your household income, when you are ready to use this tool.
You have been offered one of the following HRAs that can be used to help buy a health insurance plan on your own:
(One of these terms will appear on the notice from your employer.)
Your employer has only offered you one or more of the following:
t is a long established fact that a reader will be distracted by the readable content of a page when looking at its layout. The point of using Lorem Ipsum is that it has a more-or-less normal distribution of letters, as opposed to using 'Content here, content here', making it look like readable English. Many desktop publishing packages and web page editors now use Lorem Ipsum as their default model text, and a search for 'lorem ipsum' will uncover many web sites still in their infancy. Various versions have evolved over the years, sometimes by accident, sometimes on purpose (injected humour and the like).
t is a long established fact that a reader will be distracted by the readable content of a page when looking at its layout. The point of using Lorem Ipsum is that it has a more-or-less normal distribution of letters, as opposed to using 'Content here, content here', making it look like readable English. Many desktop publishing packages and web page editors now use Lorem Ipsum as their default model text, and a search for 'lorem ipsum' will uncover many web sites still in their infancy. Various versions have evolved over the years, sometimes by accident, sometimes on purpose (injected humour and the like).
t is a long established fact that a reader will be distracted by the readable content of a page when looking at its layout. The point of using Lorem Ipsum is that it has a more-or-less normal distribution of letters, as opposed to using 'Content here, content here', making it look like readable English. Many desktop publishing packages and web page editors now use Lorem Ipsum as their default model text, and a search for 'lorem ipsum' will uncover many web sites still in their infancy. Various versions have evolved over the years, sometimes by accident, sometimes on purpose (injected humour and the like).
t is a long established fact that a reader will be distracted by the readable content of a page when looking at its layout. The point of using Lorem Ipsum is that it has a more-or-less normal distribution of letters, as opposed to using 'Content here, content here', making it look like readable English. Many desktop publishing packages and web page editors now use Lorem Ipsum as their default model text, and a search for 'lorem ipsum' will uncover many web sites still in their infancy. Various versions have evolved over the years, sometimes by accident, sometimes on purpose (injected humour and the like).
Now the next image
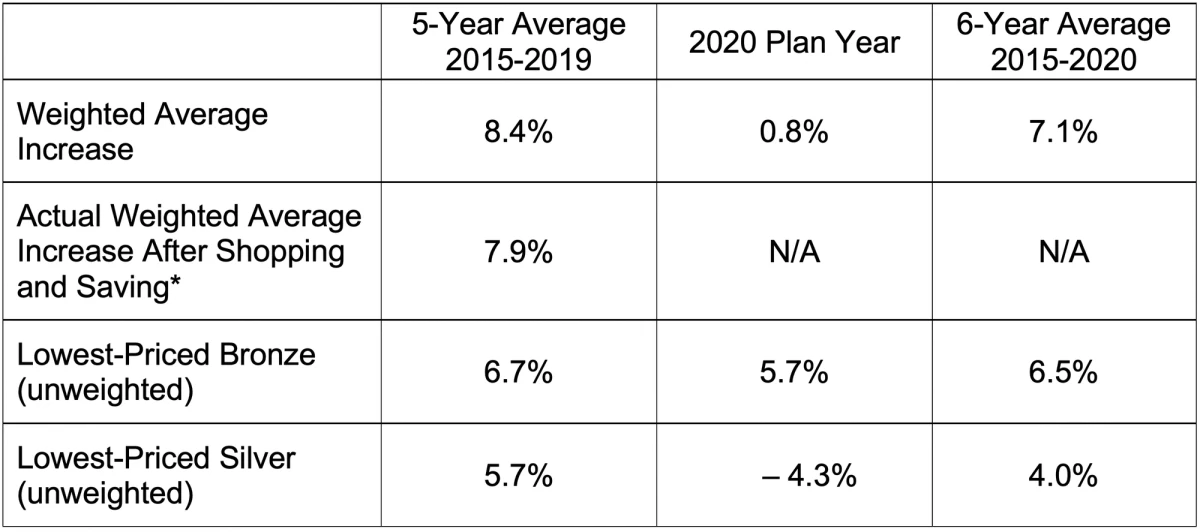
Next image after that
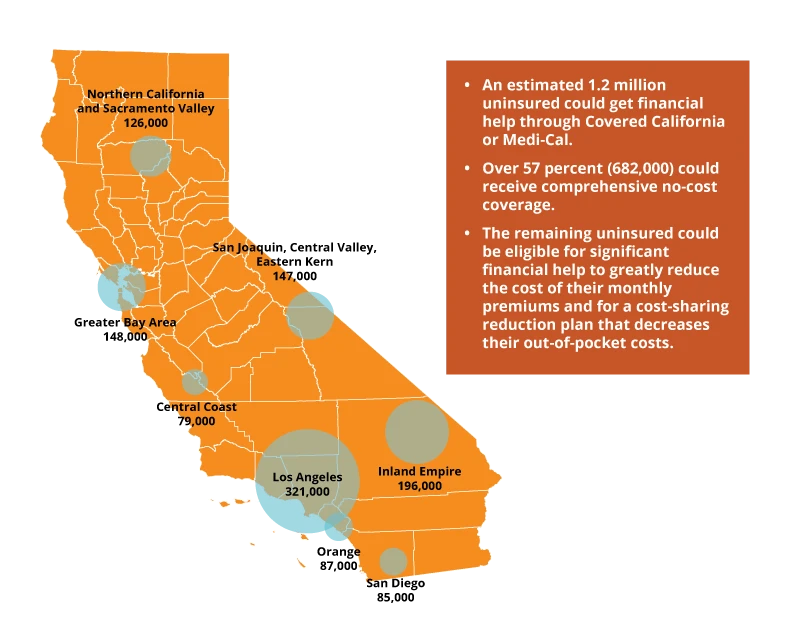
Body Optional supporting paragraph below the title.
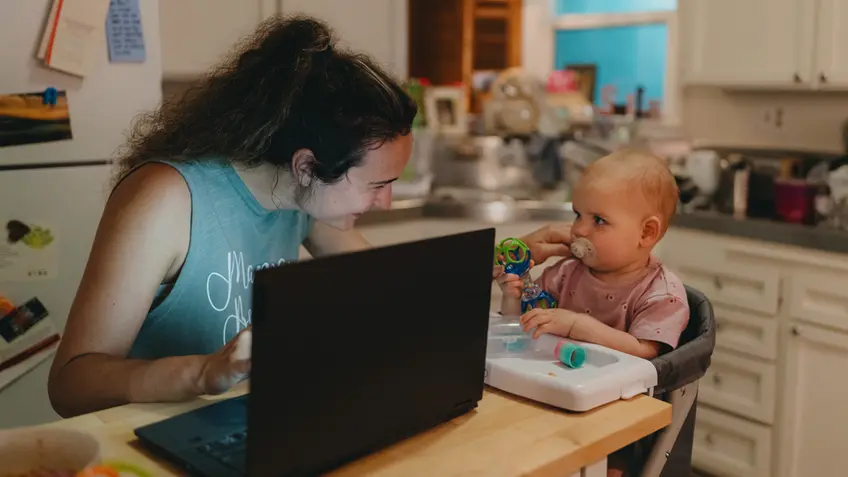
DescriptionSupporting body copy with basic formatting (bold, italic, links, and lists). Component height grows as more text is added.
Body Optional supporting paragraph below the title.
DescriptionSupporting copy for this step. Supports bold, italic, and inline links.
this is a link
DescriptionSupporting copy for this step. Supports bold, italic, and inline links.
Body Optional supporting paragraph below the title.
Optional supporting paragraph below the title.
Ver la lista completa de servicios cubiertos
Body Optional supporting paragraph below the title.
Body Optional supporting paragraph below the title.
Subheader
Best if label
Best if subcopy
Subheader
Subtitle Optional supporting text shown below the title
In a typical year, how much do you expect to use your health coverage?
Think about doctor visits, prescriptions, and medical tests you might need this year.
Once or twice
A few times
Monthly or more
What is most important when it comes to costs?
You pay for healthcare in two ways: a monthly premium and out-of-pocket costs when you get care.
Paying less each month
Somewhere in between
Paying less when I get care
Based on what you selected, you may want to explore:
Monthly Premium
What you pay each month for your plan
LOW
Deductibles
What you pay before your plan starts paying
LOW
Cost of Care
Your share of the cost when you get care
~10%
*Not all plans required that you meet your deductible before coverage began
This tool is for people who have been offered a Health Reimbursement Arrangement (HRA) by an employer to help pay for health insurance. If you are offered certain types of HRAs, you may not qualify for a tax credit to help purchase a Covered California plan. This tool will help you determine how the HRA you're offered affects your eligibility for a tax credit and what to do next.
There are several types of HRAs, and only some of them require you to use this tool. If your HRA requires use of this tool, you should have received a clear written notice from your employer explaining the terms of the HRA. You will need that notice, along with information to help estimate your household income, when you are ready to use this tool.
You have been offered one of the following HRAs that can be used to help buy a health insurance plan on your own:
(One of these terms will appear on the notice from your employer.)
Your employer has only offered you one or more of the following:
Not sure where to start?
Body Optional supporting paragraph below the title.
DescriptionSupporting body copy with basic formatting (bold, italic, links, and lists). Component height grows as more text is added.
Contact Us
Our support team can help with every step of the enrollment process
Have questions?